ACA Marketplace Health Insurance for Farmers, Ranchers & Rural Americans
Shop and enroll yourself — or have Clay do the heavy lifting for you.
Schedule Your ACA Appointment
Pick a time that works for you.
ACA Marketplace Coverage
for Real-World Working Families
Marketplace health insurance can be a great fit for:
- Families & Individuals who don’t get health insurance through an employer, or whose lowest-cost qualifying employer coverage costs more than 10.22% of household income in 2027 (using the applicable individual or family premium)
- Small Business Owners & Self-Employed people who need affordable individual coverage
- Farmers & Ranchers whose income may change from year to year
- Truck Drivers & CDL Professionals who need coverage that works while they’re on the road
- Blue-Collar & Gig Workers including contractors, delivery drivers and seasonal workers
2027 Open Enrollment Dates
Mark these important dates for 2027 Marketplace coverage.
How the ACA Marketplace Can Lower Your Health Insurance Costs
- Premium tax credits can reduce what you pay each month based on your household income, family size, and where you live.
- Some households may qualify for additional cost-sharing savings that can lower deductibles, copays, and other out-of-pocket costs on eligible plans.
- Children may qualify for Medicaid or CHIP even when the adults in the household use a Marketplace health plan.
- Compare multiple insurance companies and plan options based on premiums, deductibles, prescriptions, doctors, hospitals, and expected total costs—not just the cheapest monthly premium.
- Marketplace coverage is available during Open Enrollment and may also be available during the year after certain qualifying life events.
- Your subsidy can change when your income changes. We can help update your Marketplace application so your information and eligible savings stay accurate throughout the year.
Old Western Insurance helps you navigate the Marketplace from start to finish— from checking available savings and comparing plans to completing enrollment and making updates later when life or income changes.
As a former freight broker and current business owner, Clay Murdock understands the ins and outs of your business. He helps truck drivers, small business owners, and blue-collar workers find the right coverage and maximize your savings on brand name health insurance.
Why I Started Old Western Insurance
Hi, I’m Clay Murdock! I started Old Western Insurance because I realized farmers, ranchers, rural Americans — really, all Americans — needed better options and better guidance when it came to protecting their health, their families, and what they’ve worked for.
Before I was a licensed agent, I was unexpectedly diagnosed with Type 1 diabetes. Up until that moment, I had always thought I didn’t really need health insurance. Suddenly, I was looking at the cost of insulin and wondering how my family and I were going to afford keeping me healthy until I could enroll in coverage at the end of the year.
I was afraid medical costs could put everything my family had worked for at risk — including our family ranch. That fear was especially real because my family had already been through something similar when my aunt, who was also diabetic, was a baby and no insurance company would accept her. I found out pretty quickly how scary it was trying to figure everything out on my own. I didn’t know who to call, I didn’t know who to trust, and I doubted anyone would take my health needs as seriously as I would.
What I did know was that without the right coverage, I couldn’t live the healthy and safe life I needed to live. So I figured it out. I became an insurance broker and started Old Western Insurance so I could give other people the kind of help I wished I’d had.
Old Western Insurance was built to help real people protect their families, farms, ranches, businesses, and finances from both the expected and unexpected costs of healthcare.
When you work with me on Medicare or Marketplace health insurance, my strategy isn’t just to pick a plan and leave you with it. I give you a comprehensive review of your healthcare situation and can recommend additional coverage that may help fill the gaps, save you money, or even get you checks in the mail. I often recommend stacking on coverage for dental, vision, hospital stays, cancer, heart attack, stroke, and other major healthcare expenses.
And my work goes beyond health insurance. As someone who grew up on a farm and ranch, I believe farmers and ranchers are already stretched too thin in most cases, and too often the wrong people are getting wealthy in our industry. That’s also why I help families with financial and retirement strategies that can protect them from catastrophe, improve cash flow, and help them hold on to more of what they’ve built.
As a current MBA candidate, I’m using Old Western Insurance and my degree program to work toward making rural communities stronger. When you work with Old Western Insurance, you’re supporting agriculture and rural families nationwide.
Health Insurance Help
That Actually Feels Personal
You shouldn’t have to become an insurance expert just to make a good decision for your family, business, farm, or ranch.
We compare available subsidies, deductibles, prescriptions, doctors, hospitals, and total expected costs.
We explain the tradeoffs in plain English so you can understand what you’re buying and why it makes sense.
If your income changes, your family changes, or something goes wrong, you have someone to call who already knows your situation.
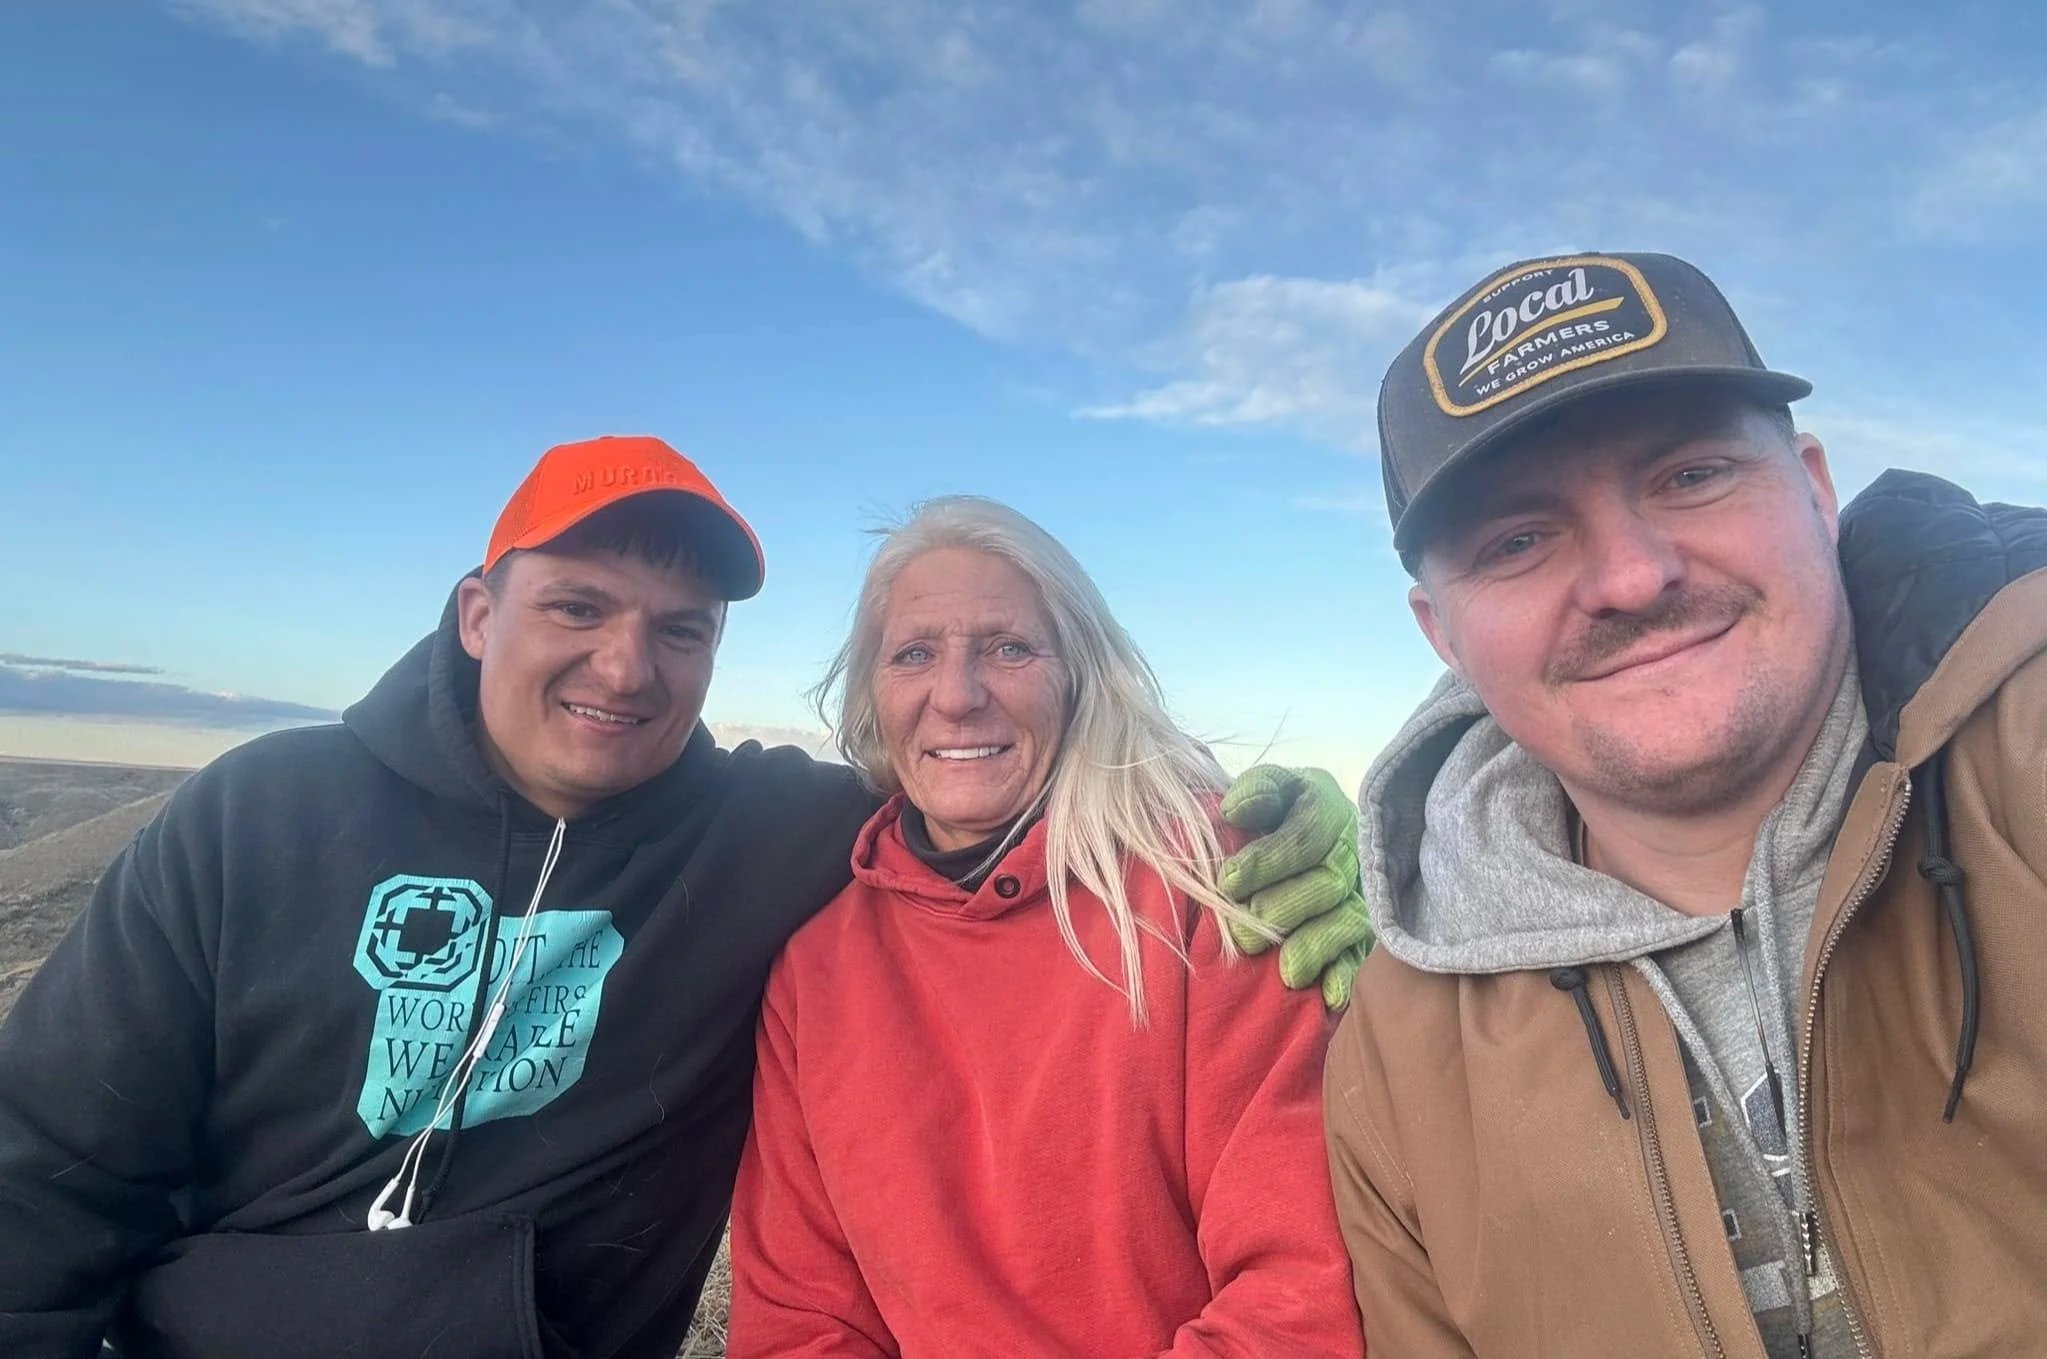
We saved Brenda $1600 a month on her health insurance! She was able to reinvest the money into hiring extra help on her family ranch! Big win for the Murdock Ranch, Inc!
Straight Answers to Your ACA Questions
-
Usually, yes! You can check this before you enroll in our estimator software.
-
Tell us—our software makes updates simple so your savings stay accurate.
-
No. You don’t pay us. You just get ongoing support when you need it.
-
Yes. Many owners and self-employed use the Marketplace for themselves and family members. We’ll walk you through options.
-
First off — don’t panic. This is actually more common than you think.
When you sign up for an ACA Marketplace plan, your monthly premium is lowered based on your estimated annual income.
If you make more than expected, your subsidy can be updated when you report it to your agent or the adjustments will be made at tax time.
Remember the subsidy is based on a rather small portion of your income so any difference you would owe is also just a small percentage of the difference.
A really rough estimate is if you make $10,000 more in a year you would only owe back around $500-$600. Which is totally doable if your income is that much more than you originally estimate.
To avoid surprises, we recommend updating your income if things change significantly. But even if you don’t, you won’t lose your insurance — and the tax impact is something you can plan for.
If you think your income is going to be over $5000 more than you estimated give us a call and we will go over the implications for you.
The rules are changing quite a bit these days with the Big Beautiful Bill and health insurance so check in with us or the marketplace if you’re unsure.
We're not tax advisors, so always check with a tax professional — but if you’d like us to walk you through how we’ve seen this affect real people in the past, give us a call. We’re happy to explain in plain English.
-
Great news — if your income drops during the year, you might qualify for even more help.
Lower income usually means higher subsidies, and in some cases, you could qualify for free or low-cost Medicaid coverage, depending on your situation. You won’t be penalized for estimating too high — but you might miss out on savings if you don’t update your income.
So definitely call us sooner than later if you realize your income is going to be significantly lower.
If your income ends up under $15,060/year (for a single person), the government may say you’re better off on Medicaid and will require you to switch. So definitely contact us if you expect a big change in income in that direction.
If you’re not eligible for Medicaid, you can still keep your plan and may even qualify for extra savings and a bigger subsidy amount.
As always, we’re not tax or legal advisors, but we’ve helped plenty of folks navigate situations like this — and we’re happy to walk you through what to expect based on your current income. Just reach out anytime.
-
When you apply for ACA health insurance, you'll be asked to estimate your total income for the year — not just what you're earning right now. This includes wages, self-employment, Social Security, unemployment, and other taxable income sources.
You don’t always have to show proof — but the rules are getting stricter. If the marketplace notices a large discrepancy (think over 10%) between your estimated income and your recent tax information, the system may flag your application and ask you to verify your income.
If that happens, you’ll get a notice with a 60-day deadline to upload documents. Don’t ignore it — if you don’t respond, your plan could be switched to full price with no subsidies or be terminated.
Insurance carriers usually aren’t responsible for refunds if you plan switches to a non-subsidized full price plan and you don’t contact them.
-
✅ For regular jobs (W-2 income):
Recent pay stubs (with gross income and pay frequency)
A letter from your employer
✅ For self-employment or gig work (1099 income):
Invoices or payment receipts
Bookkeeping records or income statements
Recent tax return (if current income is similar)
Bank statements showing business deposits
✅ For fixed income or no income:
Social Security award letter
Unemployment benefits letter
Zero-income statement or letter of support (if someone is helping you financially)
Good news: This is just a good-faith estimate, not an audit. If your income changes later, you can update it anytime to make sure your savings stay accurate.
We’re not tax advisors, but we’ve helped lots of folks through this. If you’re unsure what to submit, give us a call — we’re happy to walk you through it.
-
We’re based in Billings and the Hi-Line, and we serve clients nationwide where we’re licensed. We want you to to feel known and taken care of when you work with us!
Clay Murdock, our company owner, is a born and raised Montanan and his family has been ranching in Montana for over 100 years.
Ready to See Your Savings?
Or call/text 855-701-7113 for help now.